Blackjack
The Kelly Criterion Applied to Blackjack Bet Sizing
So I'm at a blackjack table in AC and the dealer's showing a six and I'm thinking about bankroll and optimal bet sizing and it hits me: the Kelly Criterion is the answer to how much to bet when you have an edge.
By Alex Chen3 min read
OK so I was down to my last 2,000 dollars and I'd been playing blackjack for three hours. I was keeping careful track of the cards (back when card counting was more feasible, before they made it impossible). I had an edge, maybe 2 percent, which is significant. But I didn't know how much to bet on each hand.
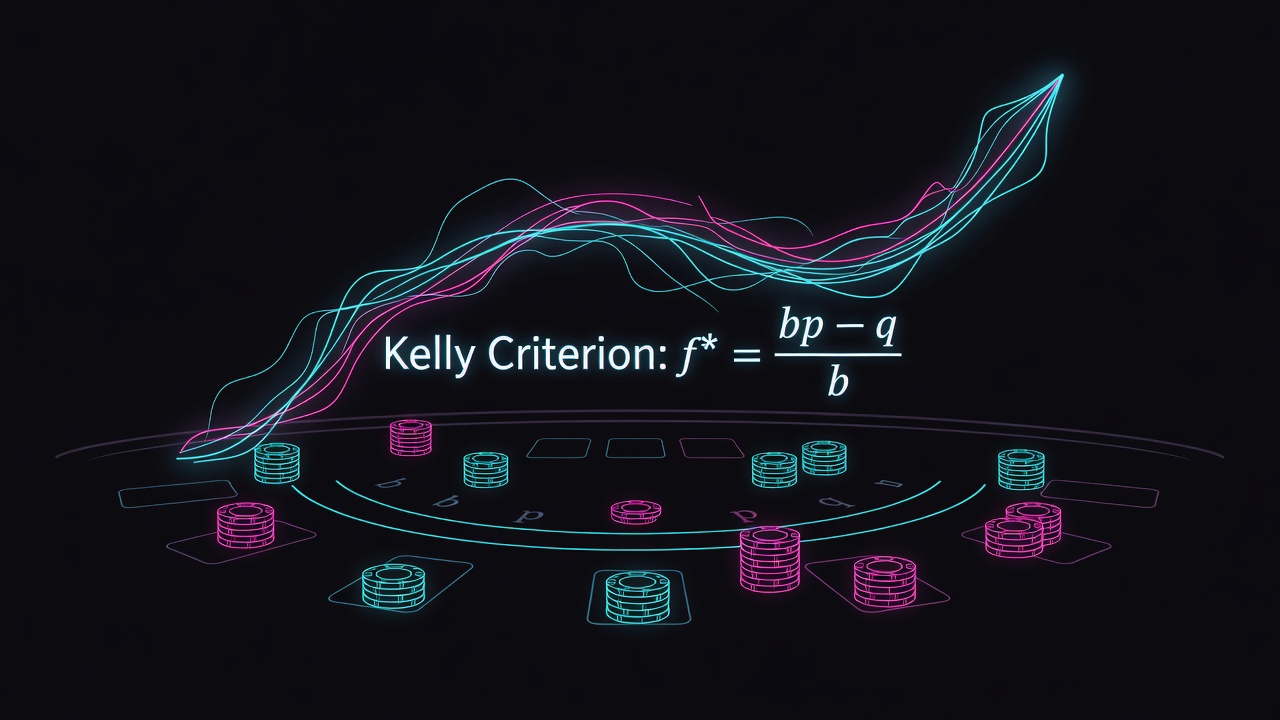
A buddy who was a math major tried to explain Kelly to me. The Kelly Criterion is a formula: bet size equals (edge times odds minus one) divided by the odds. For blackjack with a 2 percent edge and roughly even odds, this works out to about 1 percent of your bankroll per hand.
Key Concepts
So with 2,000 dollars, I should be betting about 20 dollars per hand. This seemed low given that I had an edge. But the math is clean: if you bet this fraction of your bankroll on every advantageous hand, you maximize long-term growth while minimizing risk of ruin.
The reasoning: if you bet too much, a single bad streak can wipe you out. If you bet too little, you're not taking full advantage of your edge. Kelly finds the sweet spot.
Here's the thing though: Kelly assumes you know your exact edge. Card counters who have been at this for years might know their edge is 0.8 percent. A casual player has no idea. So Kelly breaks down if you're guessing about your edge.
The other thing: Kelly assumes your edge is consistent. Blackjack edge varies by true count. When the count is favorable, your edge might be 3 percent. When it's unfavorable, you should be folding (not playing). Pure Kelly assumes constant edge, which blackjack doesn't have.
Practically, what I did: I bet 2 percent of my bankroll when my true count was favorable. Not 1 percent (pure Kelly), but 2 percent because I was fairly confident about my edge. This is sometimes called "fractional Kelly." You take Kelly's recommendation and reduce it by a safety factor.
Many professional players use half-Kelly or even quarter-Kelly because they're paranoid about ruin. If Kelly says bet 2 percent, they bet 1 percent. This reduces growth but also reduces downside risk.
The edge in blackjack is mathematically determinable. Basic strategy play has a 0.5 percent house edge. Card counting against a 4-deck shoe might give you a 0.5-1 percent player edge depending on your skill. Shuffle tracking might give you higher edge. But the point is the edge is real and you can estimate it.
Bet sizing around Kelly: when the count is neutral, bet small (quarter-Kelly maybe). When the count is favorable, bet larger (full Kelly or more). But if you bet more than Kelly suggests, you're taking on excess risk. Mathematically, this is losing strategy over time.
I ended up leaving that AC table up 1,200 dollars. Not because of Kelly sizing, but because I got lucky and the count stayed favorable. But I used Kelly to make sure my sizing was rational. I didn't overbett and risk ruin on one bad shoe.
The core insight: optimal betting is about bankroll preservation. You want to stay in the game long enough for variance to smooth out and your edge to show. Betting too much risks bankruptcy. Betting too little wastes opportunity.
Kelly is a formula that's been proven in game theory. If you have an edge and you size your bets according to Kelly (or fractional Kelly), you maximize the probability of long-term success. It's not the most exciting strategy. It won't make you rich overnight. But it works.